
PayPal Business fees for sellers depend on the payment product, not one universal business-account rate. An $80 domestic payment through PayPal wallet Checkout costs an estimated $3.28, leaving $76.72 before other deductions. Eligible Expanded Checkout card processing costs $2.60 on the same amount, using PayPal’s US business prices.
This guide covers US PayPal business accounts and USD. Examples use standard domestic pricing unless labeled otherwise. They are calculations, not personal transaction tests, and round each fee to the nearest cent with half cents rounded up. Actual account terms and rounding may differ. Net after processing is not business profit or guaranteed cash available to withdraw.
PayPal seller fees by online payment method
Match your integration and the customer’s payment choice to the appropriate row. The examples below compare receiving costs, not identical checkout experiences.
| Payment product | Domestic USD rate | Fee on $80 |
|---|---|---|
| PayPal Checkout, Guest Checkout, or Pay with Venmo | 3.49% + $0.49 | $3.28 |
| Standard credit and debit card payments | 2.99% + $0.49 | $2.88 |
| Expanded Checkout: advanced card processing, flat rate | 2.89% + $0.29 | $2.60 |
| Pay Later: standard online Checkout pricing | 4.99% + $0.49 | $4.48 |
| Direct Send/Receive Money for Goods and Services | 2.99%; no fixed fee | $2.39 |
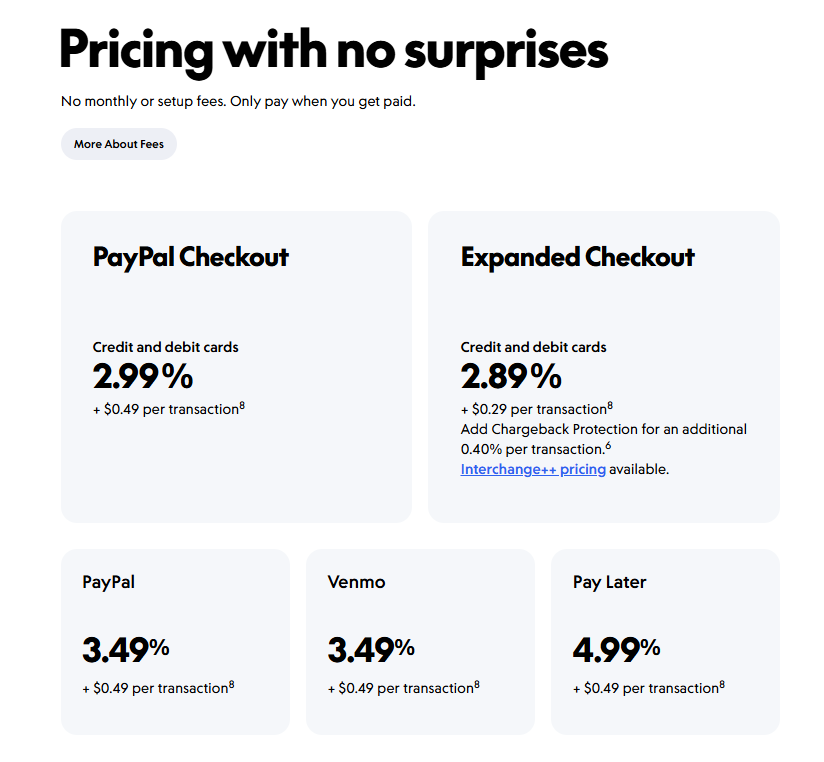
The named Goods & Services send/receive route is not the price for every sale of goods or services. Similarly, a card funding a PayPal wallet payment does not automatically establish the separate standard-card rate.
Expanded Checkout’s lower card rate comes with different responsibilities. PayPal describes greater control over checkout and risk management, with merchants handling relevant refunds, unauthorized-payment chargebacks, and compliance reporting. Compare the checkout options and responsibilities, not just the percentage. Its card rate also does not replace the PayPal-wallet rate when a customer pays that way.
Invoice and payment-link fees need their own check
Basic invoice creation and sending have no fee. When an invoice is paid, PayPal’s invoicing prices distinguish PayPal/Venmo, cards and Apple Pay, and Pay Later. For domestic invoice Pay by Bank, the rate is 1%, capped at $10 per payment. A successful $2,000 bank-paid invoice therefore has a $10 processing fee, leaving $1,990 before other costs.
The Invoicing Terms tie your rate to the payment type the customer chooses from the available options. Do not assume every account offers every method, or that funding a wallet from a bank selects invoice Pay by Bank.
The POS payment-link table prices Pay Later at 3.49% + $0.49, unlike standard online Checkout. Match the link’s product before selecting a rate.
In-person sales, keyed cards, and Virtual Terminal
PayPal Point of Sale, formerly Zettle, supports face-to-face selling. Its card-present and manual-entry prices are distinct from the browser-based Virtual Terminal product.
| Payment channel | Domestic USD rate | Fee on $80 |
|---|---|---|
| POS card-present or eligible in-person QR payment | 2.29% + $0.09 | $1.92 |
| Manual card entry through POS | 3.49% + $0.09 | $2.88 |
| Virtual Terminal | 3.39% + $0.29 | $3.00 |
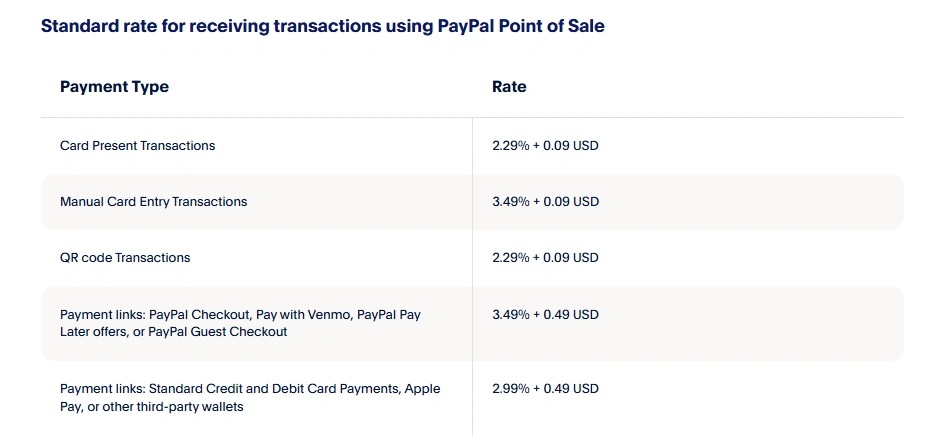
Virtual Terminal lets an approved business enter card payments in a browser for uses such as telephone orders. Its current offer shows $0 monthly fees, but transactions are not covered by the Seller Protection policy, according to its product FAQ. Do not treat it as simply another name for POS manual entry.
Tap to Pay can accept contactless payments on a compatible phone without a separate reader. Check the supported setup before buying equipment. A remotely paid order does not become a card-present transaction just because that rate is lower.
Is there a monthly fee for PayPal Business?
Opening a PayPal account is free, and basic Checkout has no monthly or setup fee. That does not make every additional payment service free.
The merchant schedule lists $14.99 per month for the optional Invoice Subscription Service. Add it only if you subscribe.
Also check exact product names. Payments Advanced and Payments Pro are different services from Advanced Credit and Debit Card Payments. Their agreements and service charges should not be imported into an Expanded Checkout estimate. The Online Payment Services Agreement identifies these products separately.
A payment gateway can add another billing layer. The Payflow agreement excludes your financial institution’s processing fees from its gateway charges. For an existing Payflow-based setup, obtain the gateway and merchant-processing costs together rather than treating the gateway’s transaction charge as the complete card fee.
Hardware is a separate purchase. PayPal’s POS offer lists a first reader at $29 for eligible new business users, additional readers at $79, and a Terminal at $199 without the barcode-scanner upgrade. Verify offer conditions, compatibility, and checkout costs; the first-reader price is not the price of every reader.
Optional fraud and chargeback tools can also change your cost. Included protection on eligible transactions is not the same as purchasing a Chargeback Protection tool. Check its price, eligible transaction types, exclusions, and loss cap before adding it.
Calculate the cost per order and per month
For an uncapped percentage-plus-fixed-fee arrangement, calculate:
Processing fee = gross payment × decimal rate + fixed feeNet after processing = gross payment − rounded fee
Use the amount actually processed, not only the merchandise subtotal. PayPal’s order amount definition accounts for items, shipping, tax, and other applicable components, less discounts. Use the final captured total for these examples; do not add shipping and tax again when they are already included.
Why small orders have a higher effective rate
Using the PayPal-wallet Checkout rate above, a $10 payment costs $0.84 after rounding—8.40% of the payment. A $100 payment costs $3.98, or 3.98%. The fixed charge takes a larger share of a small order.
The effective processing rate is processing fee ÷ gross payment × 100. It describes the cost of that transaction; it does not mean your published percentage has changed.
Example: 220 sales through three payment channels
Consider this hypothetical month for a US business. Every payment is domestic USD, there are no refunds or disputes, and no optional services are enabled.
| Payment channel | Sales in the month | Gross receipts | Processing fees |
|---|---|---|---|
| PayPal-wallet Checkout | 120 × $80 | $9,600.00 | $393.60 |
| Expanded Checkout cards | 60 × $80 | $4,800.00 | $156.00 |
| POS card-present | 40 × $50 | $2,000.00 | $49.60 |
| Total | 220 payments | $16,400.00 | $599.20 |
The business retains $15,800.80 after processing, with an effective processing rate of approximately 3.65%. This is not an industry average or a forecast for your store.
To turn that into your payment-cost budget, add only the subscriptions, platform charges, withdrawals, and other expenses your setup actually incurs. Keep equipment purchases in a separate first-period total. Do not add a reserve or a refunded sale amount as though it were another processing fee.
International sales and withdrawals add separate costs
For international PayPal Checkout receipts, the US schedule adds 1.50 percentage points. Receiving USD does not make an overseas transaction domestic.
An $80 international wallet-Checkout payment therefore uses 80 × (0.0349 + 0.015) + 0.49. The estimated fee is $4.48, leaving $75.52 before conversion or withdrawal. That is $1.20 more than the domestic example.
Interchange-based card arrangements need their own calculation. Under the card-payment agreement, pass-through costs form part of that pricing; a quoted markup alone is not the total fee.
Currency conversion is not the cross-border fee
PayPal’s transaction exchange rate already includes its conversion spread. Identify the amount being converted and the currencies involved, then use that quoted rate once. Do not convert the balance and deduct the spread again.
Receiving a foreign-currency payment, converting an existing balance, and later withdrawing can involve different stages. Keep the costs in their respective currencies until you have a valid basis for combining them.
Standard versus instant bank withdrawal
For US business accounts, the withdrawal schedule lists no PayPal fee for a standard transfer to an eligible linked bank without conversion. Instant bank transfers cost 1.50%, with a $0.50 USD minimum. Do not import a personal-account fee cap.
From the domestic $80 wallet sale, $76.72 remains after processing. An instant withdrawal of that amount produces a modeled $1.15 withdrawal fee, leaving $75.57 if the fee is deducted from the transfer and no other charges apply.
The withdrawal percentage is applied to $76.72, not the original $80. Confirm the amount delivered in the transfer preview; a maximum transfer amount is a transaction limit, not a maximum fee.
Refunds, disputes, and chargebacks: what can you lose?
Refunds retain the original receiving cost
For goods-and-services payments, PayPal charges no new fee to issue a refund, but does not return the original receiving fees. Do not budget as if only the fixed portion is retained.
In the $80 wallet-sale example, a full refund returns $80 to the buyer while the original $3.28 processing cost remains. That $3.28 is not charged a second time. Your monthly budget already includes it if it counted the original payment.
Dispute and chargeback fees are different categories
| Fee category | Listed USD amount | Relevant distinction |
|---|---|---|
| Standard Dispute Fee | $15 | PayPal-account or guest-checkout dispute process, subject to exemptions |
| High Volume Dispute Fee | $30 | Higher dispute tier when its conditions apply |
| Chargeback fee | $20 | Card-issuer chargeback outside the PayPal-account or guest-checkout route |
PayPal’s dispute guidance places sellers in the high-volume tier when the dispute ratio is at least 1.5% and they had more than 100 sales in the previous three full calendar months. An ordinary Resolution Center inquiry that never becomes a claim does not automatically attract the Standard Dispute Fee.
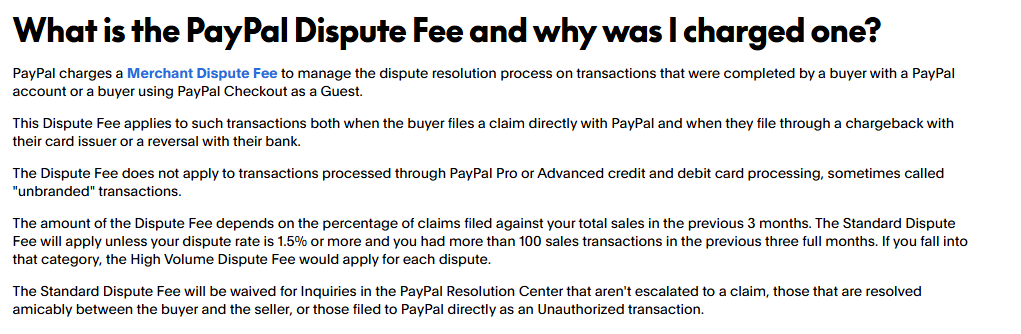
The dispute-fee rules also waive the standard fee in specified cases, including claims decided in the seller’s favor and qualifying protected transactions. High-volume exemptions are narrower. The separate chargeback fee can apply even if the seller wins. Do not automatically stack both fee categories on one case.
Seller Protection is conditional, not a blanket guarantee
For eligible physical shipments, keep the delivery evidence required by PayPal Seller Protection and ship to the transaction address. Digital goods require qualifying fulfillment evidence. An invoice or tracking number alone does not guarantee that every claim qualifies.
The same policy excludes Significantly Not as Described claims and card-issuer Item Not Received claims. Review the eligibility rules for your product and payment route before assuming a disputed order’s value is covered.
Why your available balance can differ from net sales
PayPal may hold payments because of factors such as a new selling history, unusual activity, or customer problems. A recorded payment and an available balance are different things.
The reserve provisions also allow business funds to be held against reversal risk. A reserve restricts availability; it is not another routine processing deduction.
Keep three figures separate: gross sales, net after fees, and funds currently available. Paying for instant withdrawal does not make held funds available. Check the account’s release requirements rather than adding the held amount to your fee calculation.
Reduce costs without misclassifying payments
- Review the actual product. Compare eligible Checkout options against the integration work and risk responsibilities you will take on. Request a written quote where custom merchant pricing is available; do not assume discounts apply automatically.
- Audit optional services. Remove a subscription only after checking what you would lose. For a gateway-based arrangement, include the separate processor bill. For marketplace sales, first establish who processes the payment; the buyer choosing PayPal does not prove you owe an additional direct-merchant charge.
- Ask about low-ticket pricing. Micropayments pricing requires approval and does not cover every payment type. Confirm how your agreement applies before assuming every small sale receives a lower rate.
- Choose withdrawal timing deliberately. Standard transfer may suit your cash needs without the instant-transfer charge. Fewer withdrawals do not necessarily save money on a purely proportional fee; minimums and other pricing features matter.
Build payment expenses into your overall pricing rather than inventing a PayPal-only charge. The US agreement prohibits acceptance surcharges, mislabeling purchases as personal payments, and using donation services for ordinary sales. It also sets checkout-presentation rules; check those before trying to steer customers to a different method.
Check your actual PayPal fees
For an individual sale, open Activity and select the transaction, following PayPal’s fee-checking instructions. For a month’s activity, use the report-download instructions to generate an appropriate report.
The Activity Download report includes Gross, Fee, Net, Currency, and Transaction ID. Match records by transaction and currency rather than comparing one order with a bank transfer that combines multiple receipts.
Watch the fee sign: if an export records a deduction as a negative amount, do not subtract it twice. Check the applicable product, transaction date, international status, and account-specific pricing before treating a difference as an error.
Start with the channel that processes your sales, then add the costs you actually use. A lower card percentage, a free basic account, or a fee-free standard withdrawal describes only part of the setup. Your transaction mix and selected services determine the useful comparison.
Last verified: October 18, 2026.