
For lower payment fees, start with GoCardless for bank collections, Stripe for online card payments currently processed through PayPal Checkout, and Wise Business for eligible client bank transfers. Helcim is worth comparing when you need both card and bank payments, while Square can make sense when its selling tools fit your business. None is cheaper than every PayPal product.
This comparison of the best PayPal alternatives for lower fees uses US business pricing and domestic USD payments unless stated otherwise. Recommendations are based on published fees, payment capabilities, and the conditions behind potential savings. The examples are calculations, not personal transaction tests or guaranteed quotes.
The best options at a glance
| Alternative | Best reason to consider it | Relevant US pricing and limitation |
|---|---|---|
| GoCardless | Collecting invoices or recurring payments by bank debit | Standard domestic ACH: 0.5% + $0.05, capped at $5 per payment. Customers must authorize bank collection. |
| Stripe | Online card payments with straightforward standard pricing | 2.9% + $0.30 for domestic cards. Invoicing and subscription billing can add fees. |
| Wise Business | Receiving client payments through eligible local bank details | No receiving fee for supported domestic non-wire payments. US receiving features have a $31 one-time setup fee; conversion and other transfer costs remain separate. |
| Helcim | Comparing card costs against your actual transaction mix | At its lowest-volume tier, online cards cost interchange and applicable network charges plus 0.50% + $0.25. That markup is not the total fee. |
| Square | A combined invoicing, online-selling, and in-person workflow | Square Free online and invoice card payments: 3.3% + $0.30. Lower paid-plan rates require a subscription. |
First, identify the PayPal fee you actually pay
A comparison against “PayPal’s fee” is incomplete unless it names the product. PayPal separates Checkout, standard card processing, advanced card processing, invoicing, and account-to-account Goods & Services payments. Its domestic US Send/Receive Money for Goods and Services rate is 2.99% without a fixed fee, which is different from the checkout rates compared below. See the official merchant fee schedule.
PayPal also offers bank-payment options: invoice Pay by Bank costs 1%, capped at $10, while its separate ACH Services rate is 0.80%, capped at $5. These belong to different products; confirm which is available for your account and payment flow rather than applying either rate to every invoice. Both appear in the US fee schedule.
This creates two distinct opportunities: changing providers while keeping the payment method comparable, or changing how customers pay. Replacing card payments with bank payments may produce a larger saving, but that does not prove the new provider has cheaper card processing.
1. GoCardless: a strong choice for lower-cost bank collections
GoCardless is a good starting point for service businesses collecting invoices, retainers, or subscriptions from customers willing to authorize bank payments. Its US Standard plan charges 0.5% + $0.05 for domestic ACH payments, capped at $5 per transaction, with no required monthly subscription. Optional add-ons cost extra.
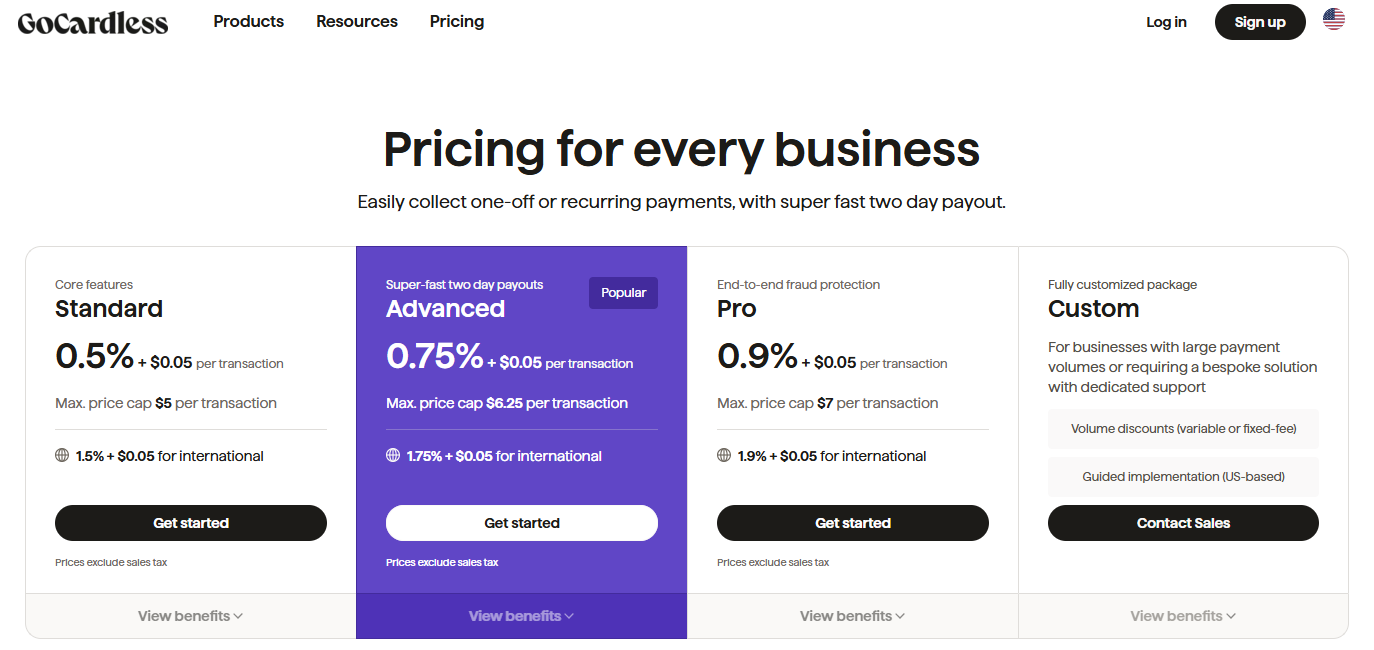
That produces a $2.55 processing fee on a $500 collection. Compared with the $5 fee for the same amount through PayPal’s invoice Pay by Bank option, the processing saving is $2.45.
The trade-off is the payment method. Customers authorize an ACH debit rather than simply choosing a card or wallet. GoCardless supports hosted authorization pages and one-off or recurring collection. Its pricing also lists a $5 failure fee; the faster two-day payout feature belongs to Advanced and Pro, not Standard. Check the plan and additional-fee details before choosing solely on the headline rate.
Choose it for a bank-collection workflow you can actually use. Do not replace a required card checkout with bank debit merely because the percentage is lower.
2. Stripe: lower standard online card fees than PayPal Checkout
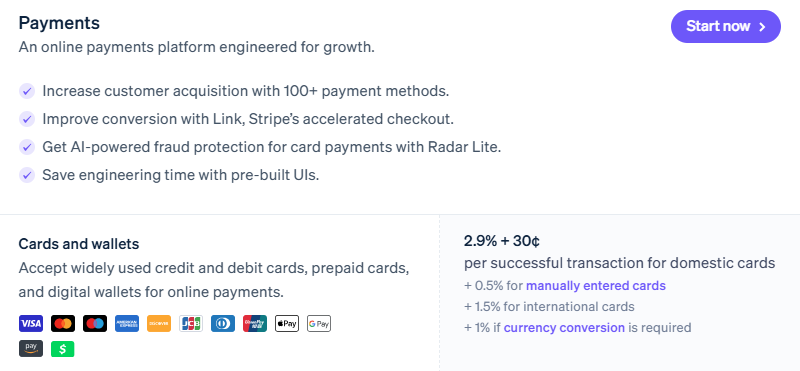
Stripe’s standard domestic US card rate is 2.9% + $0.30. That is lower than PayPal Checkout’s 3.49% + $0.49, but it does not beat PayPal’s advanced card-processing rate. Compare the exact products in Stripe’s pricing and PayPal’s business pricing.
| Payment product | Domestic USD rate | Fee on $20 | Fee on $100 |
|---|---|---|---|
| PayPal Checkout | 3.49% + $0.49 | $1.19 | $3.98 |
| PayPal standard cards | 2.99% + $0.49 | $1.09 | $3.48 |
| PayPal advanced cards | 2.89% + $0.29 | $0.87 | $3.18 |
| Stripe standard cards | 2.9% + $0.30 | $0.88 | $3.20 |
For a $100 payment, Stripe saves $0.78 against PayPal Checkout and $0.28 against PayPal standard cards. Against PayPal advanced cards, it costs $0.02 more. Before migrating an integration for a small difference, check whether the relevant PayPal product is available to your business.
Add invoicing or billing fees when you need those products
Stripe Invoicing Starter adds 0.4% per paid one-time invoice to payment-processing fees. Standard pay-as-you-go Billing charges 0.7% of billing volume and includes recurring invoices; do not add the one-time invoicing percentage again to the same subscription. Stripe explains this distinction in its Invoicing pricing guidance.
For example, a $500 domestic card payment through Invoicing Starter costs $14.80 for processing plus $2 for invoicing: $16.80 total. The PayPal standard-card invoice example below costs $15.44. Stripe’s lower base card rate does not make this particular invoicing setup cheaper.
Stripe is most compelling here when its standard payment product meets your needs without additional invoicing or billing charges. A simple payment link may suit a one-off request, but it is not a substitute for every invoice-management feature.
3. Wise Business: useful for client bank transfers and currency management
Wise Business is worth considering when clients can transfer money to your eligible local account details. Its US pricing lists free receipt of supported domestic non-wire payments, including USD ACH receipts, and a $31 one-time fee to unlock receiving features. Currency conversion, sending money onward, and other payment routes have separate charges. See Wise Business US pricing.
The distinction between ACH and wire matters. Wise’s USD receiving instructions list no receiving fee for ACH, but $6.11 for a USD wire or SWIFT receipt. Account-detail availability depends on eligibility, and intermediary banks can add charges on international routes.
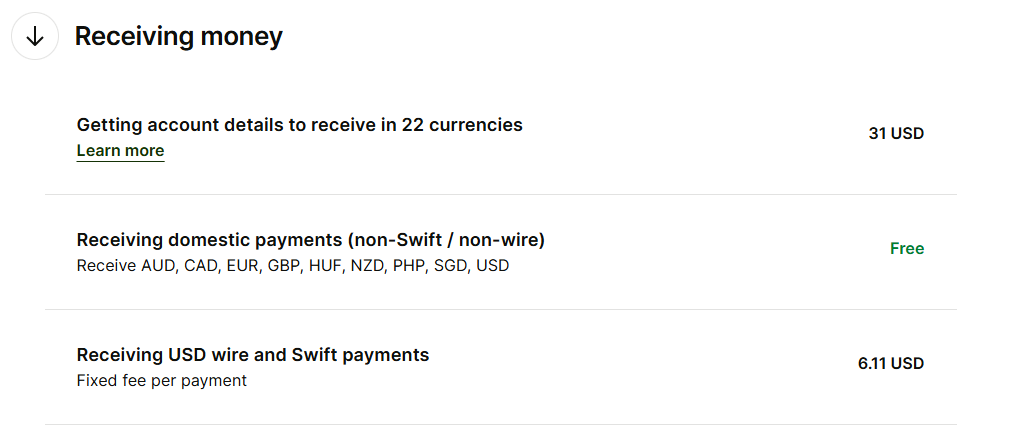
For an already-configured eligible account, a $500 domestic ACH receipt therefore has no Wise receiving fee. That is a receiving-stage comparison, not a claim that the entire payment is free: the sender’s bank may charge, and you may later convert or transfer the money elsewhere.
Compare international quotes by the amount that reaches you
For a cross-border client payment, record the sender’s country, funding method, sending currency, your receiving currency, and the final withdrawal destination. Then hold either the sender’s total outlay or your target receipt constant across quotes.
Compare the final amount after conversion and any onward-transfer charges. Do not add an assumed exchange-rate markup to a quote that already includes its conversion cost, or compare Wise’s receiving fee alone with PayPal’s processing-and-conversion total.
This recommendation concerns customer-initiated bank transfers. It is not a promise of a drop-in replacement for a consumer card checkout or an automated bank-debit subscription. Choose Wise when the client-payment route and currency handling fit your business, then verify the complete quote.
4. Helcim: compare actual card costs, with bank payments alongside
Helcim offers card processing without an account monthly fee. Its lowest-volume tier, up to $50,000 in monthly card volume, adds 0.50% + $0.25 for keyed and online payments to pass-through costs. Those figures are the processor’s markup, not an all-inclusive card rate. See Helcim’s pricing tiers.
With interchange-plus pricing, your total depends on the underlying card and network charges. Ask for a comparison using your recent processing statement and actual mix of cards rather than treating a provider’s advertised average as your guaranteed rate.
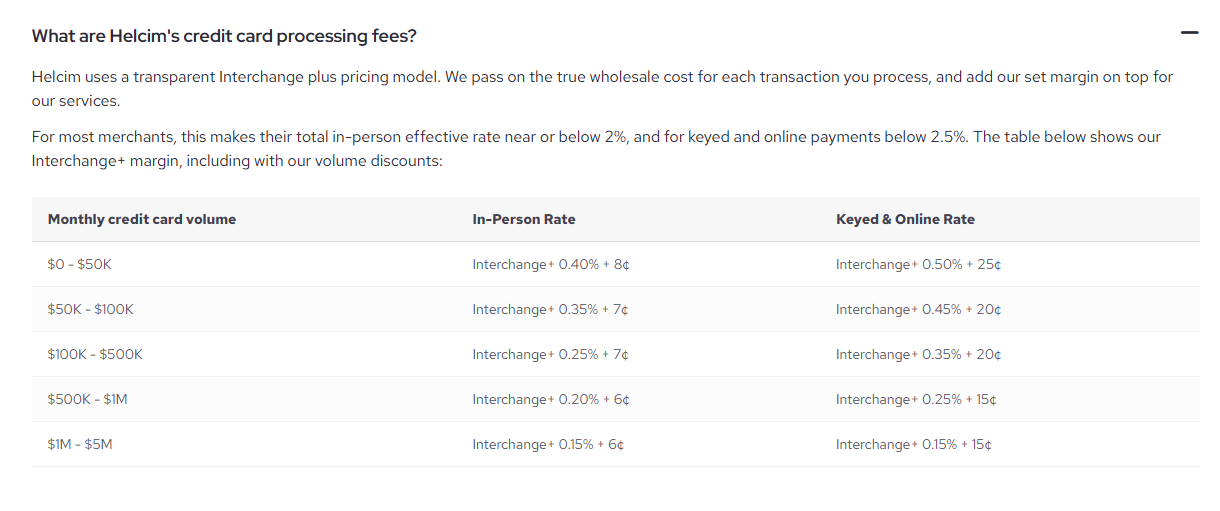
A useful test: on a $100 online payment, Helcim’s stated markup is $0.75. To beat the $3.18 PayPal advanced-card example, all applicable pass-through charges would need to total less than $2.43, assuming no other charges. That is a break-even condition, not an assumed interchange quote.
For one-off bank collection, Helcim’s ACH product charges 0.5% + $0.25, giving a $2.75 fee on $500. Its published pricing caps the base fee at $6, with additional pricing above $25,000. Recurring payments have a separate 0.4% charge, so do not reuse the one-off example for subscriptions without adjusting it.
Helcim merits a quote when you want to evaluate cards and bank collection together. Its card savings must be demonstrated with your transactions; its markup alone cannot establish the winner.
5. Square: useful selling tools, but check the channel and plan
Square is a practical candidate for businesses combining online sales, invoices, and in-person payments. However, its fee schedule distinguishes the payment channel: Square Free online and invoice card payments cost 3.3% + $0.30, while Online API payments have separate pricing. Do not apply the API rate to every Square online transaction.
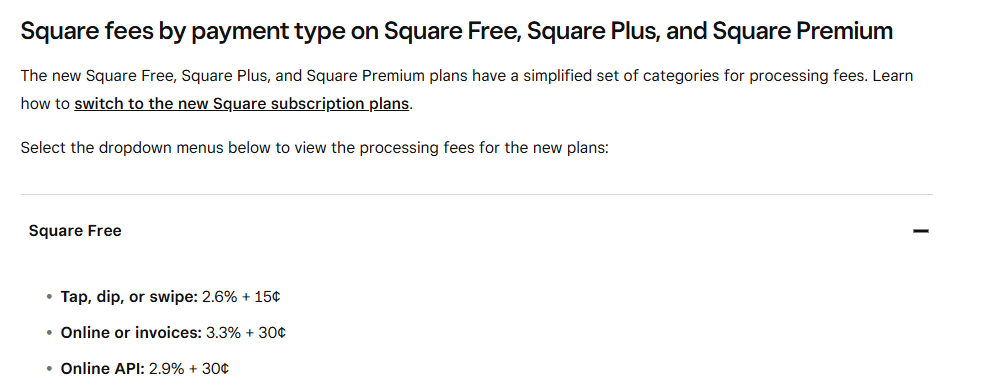
On a $100 ordinary online payment, Square Free costs $3.60. That saves $0.38 against PayPal Checkout, but costs more than the $3.48 PayPal standard-card and $3.18 advanced-card examples.
Choose Square when its workflow is valuable to you, not because every Square transaction is cheaper. These examples concern customer-paid online transactions, not manually entered or card-on-file charges.
When does Square Plus pay for itself through lower online fees?
Square Plus costs $49 per month per location and reduces the relevant online card rate to 2.9% + $0.30. Compared with Square Free, the percentage falls by 0.4 percentage points while the fixed transaction charge stays the same.
The fee-only break-even calculation is $49 ÷ 0.004 = $12,250 in qualifying monthly online sales per location.
At 100 payments of $100 each, Square Free costs $360. Square Plus costs $320 in processing plus its $49 subscription: $369. The lower transaction rate still leaves Plus $9 more expensive that month.
This calculation excludes taxes, extra services, and the value of paid-plan features. It also excludes API and in-person sales. Above the threshold, the online fee reduction can justify the subscription on its own; below it, the additional tools would need to provide the remaining value.
What changes on a $500 client payment?
The following example separates bank collection from card payment and includes Stripe’s one-time invoicing charge where that product is used. Each row represents one successful $500 domestic USD payment under the named setup.
| Payment setup | Fee calculation | Estimated fee |
|---|---|---|
| GoCardless Standard ACH | 0.5% + $0.05 | $2.55 |
| Helcim one-off ACH | 0.5% + $0.25 | $2.75 |
| PayPal ACH Services | 0.8% | $4.00 |
| Stripe ACH processing only | 0.8% | $4.00 |
| PayPal invoice Pay by Bank | 1% | $5.00 |
| Stripe ACH with Invoicing Starter | $4 processing + $2 invoicing | $6.00 |
| PayPal invoice, standard card payment | 2.99% + $0.49 | $15.44 |
Moving from the PayPal card-invoice example to GoCardless saves $12.89, but changes both provider and payment method. Moving from PayPal’s invoice bank payment to GoCardless saves $2.45—a more comparable bank-collection comparison.
Stripe’s base ACH fee matches PayPal ACH Services here. Adding Invoicing Starter takes Stripe above PayPal’s invoice Pay by Bank fee. Separately, Stripe’s US bank-payment pricing lists an additional charge when Financial Connections instant verification is used; include that when your chosen flow requires it.
Bank collection also changes payment handling. ACH confirmation and settlement are not the same event, and payments can fail or be returned. Review the relevant collection status before treating a payment as available funds; Stripe’s ACH documentation explains these distinctions.
When Shopify Payments or Payoneer deserves a closer look
Shopify Payments: strongest as part of an existing Shopify decision
Shopify Payments is worth evaluating when you already operate an eligible Shopify store. Use the processing rate for your actual plan and check country and business eligibility. Moving to a paid commerce platform solely for a lower processing percentage requires a different cost calculation from activating payments on a store you already run.
Do not automatically add a Shopify third-party transaction fee to every PayPal order. Shopify’s billing guidance says PayPal transactions are exempt from those fees when Shopify Payments is your primary gateway.
For an existing store, compare incremental costs. For a platform migration, include the new subscription, required apps, and transition expense. A saving that excludes the platform you must buy is not a complete saving.
Payoneer: useful for some business payouts, not automatically cheaper
Payoneer may fit marketplace payouts or cross-border business clients, but price the actual receipt and withdrawal route. Its pricing page lists an annual account fee of $29.95 when receipts fall below $6,000 during a consecutive 12-month period, subject to account and plan conditions. This can matter when payments are occasional.
Its Payment Link FAQ also limits that particular feature to B2B payments rather than consumer store checkout. Do not extend that product to a use case it does not support.
Include receiving, conversion, and withdrawal charges in your comparison. A fee paid by your client still exists—it has changed sides, not disappeared.
Is there a genuinely free alternative for business payments?
Sometimes, but the bank and account matter. Chase does not charge an additional Zelle transaction fee for eligible business use, although account charges may apply. By contrast, Truist lists a 1% business receiving fee, capped at $15.
That makes “Zelle is free for businesses” an unreliable blanket claim. Confirm that your bank supports Zelle for your specific business account, then check receiving fees and limits. Consumer availability does not establish business eligibility; consult Zelle’s small-business guidance.
Check the full cost before switching
Use a representative month of your own transactions rather than choosing a provider from one headline rate. Keep domestic cards, international cards, bank payments, and currency conversions separate.
- Confirm eligibility and the exact product. Check your registered business country, business activity, account approval requirements, and supported customer payment methods.
- Calculate each transaction. Apply the appropriate percentage, fixed charge, minimum, and cap to each payment—not a per-payment cap to your monthly total.
- Add required services. Include subscriptions, invoicing, billing, verification, selected integrations, and the payout options you actually need. Separate one-time migration costs from recurring charges.
- Check unsuccessful and refunded payments. Include expected returns, disputes, and refund treatment. For example, PayPal does not return the original receiving fee when you refund a Goods & Services payment.
- Test the complete payment journey. Confirm what the customer must do, whether another account is required, when funds become available, and how payments reconcile with your records.
For a comparable monthly view, calculate included payment costs ÷ processed volume × 100. This effective rate is useful only when both providers include the same cost categories. Compare the final amount received separately when currencies differ.
Review checkout presentation and surcharge rules before changing an existing integration. PayPal’s US User Agreement contains payment-presentation requirements, prohibits PayPal acceptance surcharges, and prohibits asking buyers to classify purchases as personal payments. None of those is a fee-saving workaround.
Which alternative should you choose?
For bank-paid invoices, start by comparing GoCardless with your existing PayPal bank option. For online cards, calculate Stripe against the PayPal product you actually use, including advanced card processing where available. For international client transfers, obtain a complete Wise quote through the route your client can use.
Request a statement-based Helcim comparison when your card mix justifies closer analysis. Choose Square when its workflow earns its place, and upgrade plans only when fee savings or useful features cover the subscription.
You do not have to replace every payment method at once. Validate a suitable alternative with representative transactions, then decide whether to replace PayPal or retain multiple supported options. The right choice reduces the cost of the payments you can realistically move without dropping functionality your customers or business need.
Last verified: October 18, 2026.