
PayPal international transaction fees depend on what you are paying for, which account markets are involved, how you fund the payment, and whether currency conversion occurs. A personal transfer, an overseas customer payment, and an international purchase do not use one universal fee. Start with your transaction type below.
This guide uses US PayPal account pricing. All dollar amounts are USD. Sending examples calculate the US sender’s costs—not a foreign recipient’s eventual bank receipt. Examples use standard pricing, exclude special waivers and account-specific arrangements, and omit conversion unless explicitly stated. Calculated amounts are shown to the nearest cent; the actual transaction quote and applicable terms control.
PayPal international transaction fees at a glance
| Your transaction | Who pays the listed fee? | US fee before currency conversion |
|---|---|---|
| Send a personal payment abroad using balance or bank | US sender | 5%, with a $0.99 minimum and $4.99 maximum. Card funding can add charges. |
| Receive a genuine personal payment from abroad | Eligible US recipient | No receiving fee when no conversion is involved. |
| Receive a payment from an overseas customer | US seller | The relevant product’s base fee plus its international supplement; see the commercial examples below. |
| Make an ordinary purchase from an overseas merchant | US buyer | No PayPal purchase fee without conversion. Card-issuer charges are separate. |
PayPal classifies payments by the parties’ account markets, with some markets grouped for fee calculations. A UK customer paying a US seller in USD can therefore still create an international transaction. Selecting dollars does not change the account markets. See the definitions in the official fee schedule.
Sending money abroad to friends or family
For a personal transfer, calculate the international component first. Apply the minimum if the percentage result is too small, or the maximum if it exceeds the cap. The minimum is not an extra charge added to the percentage.
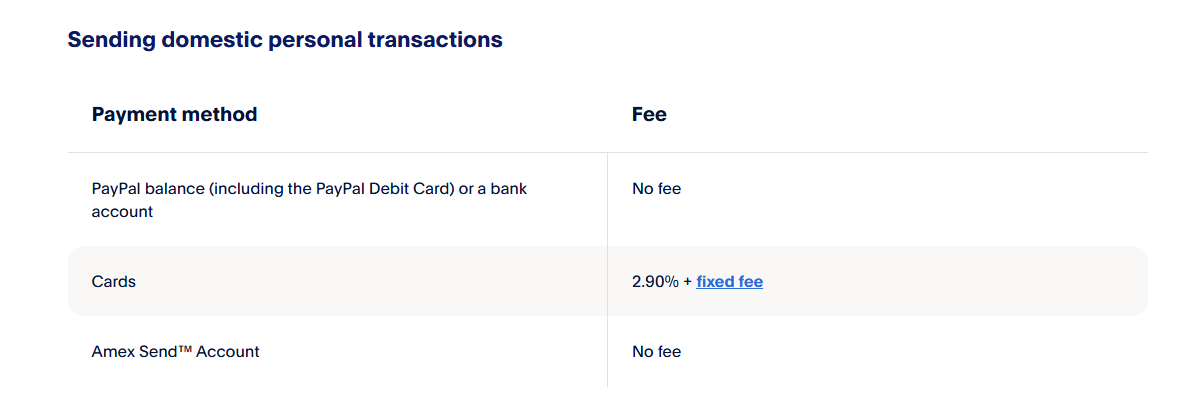
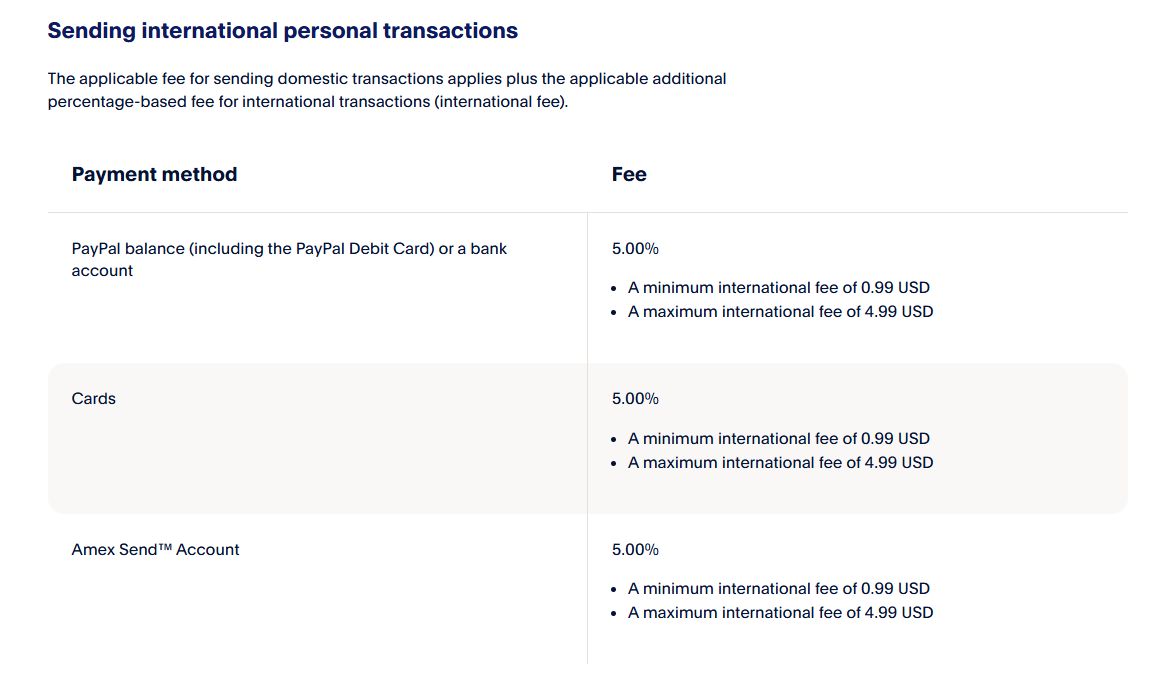
Balance or bank: how the minimum and maximum work
Assume a US sender pays an eligible UK personal recipient who accepts USD. The following examples use balance or bank funding, no conversion, and fees added on top of the amount sent.
| Amount sent | 5% before limits | International fee | US sender’s total |
|---|---|---|---|
| $10.00 | $0.50 | $0.99 | $10.99 |
| $50.00 | $2.50 | $2.50 | $52.50 |
| $1,000.00 | $50.00 | $4.99 | $1,004.99 |
The $1,000 example demonstrates the cap: the international component is $4.99, not $50. “Send $1,000” here means a $1,000 payment plus the sender’s fee, not a $1,000 all-inclusive budget.
Card funding: why the total can exceed $4.99
For the standard Cards category, add 2.9% plus a currency-based fixed fee to the international component. The fixed fee is $0.30 when USD is received. The consumer schedule groups the PayPal Debit Card with balance funding, so do not apply ordinary card pricing to it automatically.
For the same $1,000 USD personal payment, using standard card funding:
International component = $4.99Card-funding component = $1,000 × 0.029 + $0.30 = $29.30Total PayPal sender fees = $34.29US sender’s total = $1,034.29
The international cap does not limit that separate funding charge. A credit-card issuer may also charge a cash-advance fee, as noted in PayPal’s personal-payment terms. That issuer charge is outside this example.
These calculations do not establish what the UK recipient can ultimately withdraw. Check the recipient’s own market rules for any receiving, conversion, or withdrawal costs rather than applying US rules to both parties.
Receiving international payments for goods or services
A client invoice or sale is a commercial payment, not a personal transfer simply because the recipient uses a personal account. PayPal’s payment-purpose guidance distinguishes purchases from Friends and Family payments and explains that the seller pays the receiving fee.
For a US seller receiving USD from a UK customer, these standard flat-rate examples include the applicable international percentage. They exclude conversion and other deductions.
| Receiving product | International USD rate | Fee on $100 | Net received |
|---|---|---|---|
| Send/Receive Money for Goods and Services | 4.49%; no fixed fee | $4.49 | $95.51 |
| PayPal Checkout | 4.99% + $0.49 | $5.48 | $94.52 |
| Standard card payments | 4.49% + $0.49 | $4.98 | $95.02 |
| Advanced card payments, flat-rate pricing | 4.39% + $0.29 | $4.68 | $95.32 |
Example: a $1,000 overseas Checkout payment
For Checkout, the base percentage and international addition combine as 3.49% + 1.50% = 4.99%. Applying that to a $1,000 gross payment:
Receiving fee = $1,000 × 0.0499 + $0.49 = $50.39Net before conversion or withdrawal = $949.61
Do not confuse 4.99%, the Checkout percentage in this example, with the $4.99 personal-transfer cap. Nor should you calculate the international percentage on the domestic fee: here it applies to the gross payment.
An invoice’s payment method also matters. Match it to the invoicing fee table; an invoice does not establish one universal receiving rate. Likewise, a buyer using a card does not by itself identify the seller’s processing product.
Interchange pricing is a separate case. The merchant schedule excludes Advanced Card Payments on Interchange Plus Plus pricing from the additional international percentage. Its product agreement still passes through interchange, card-company, and bank foreign-handling costs. “No additional percentage” does not mean free international processing.
Currency conversion: a separate cost inside the exchange rate
For the purchase and personal-payment conversions covered here, the US schedule lists a 4% conversion spread; other conversions are listed at 3%. Both allow a different amount to be disclosed during the transaction. These are conversion-activity categories, not simply “personal” versus “business” account rates. Check the currency-conversion section.
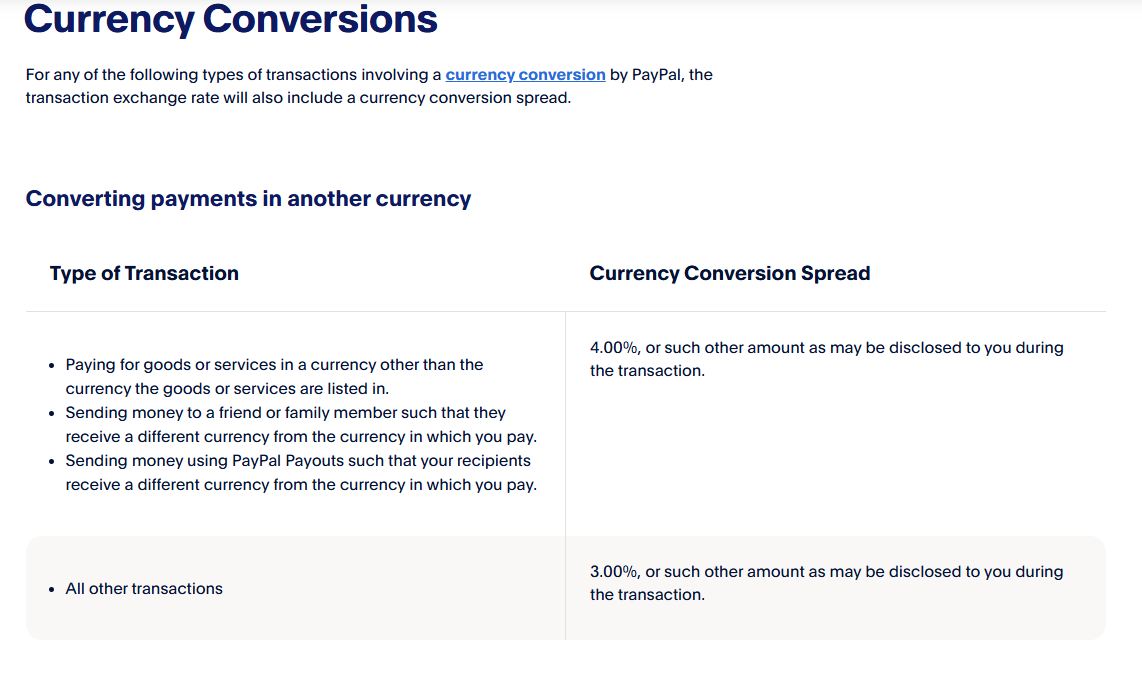
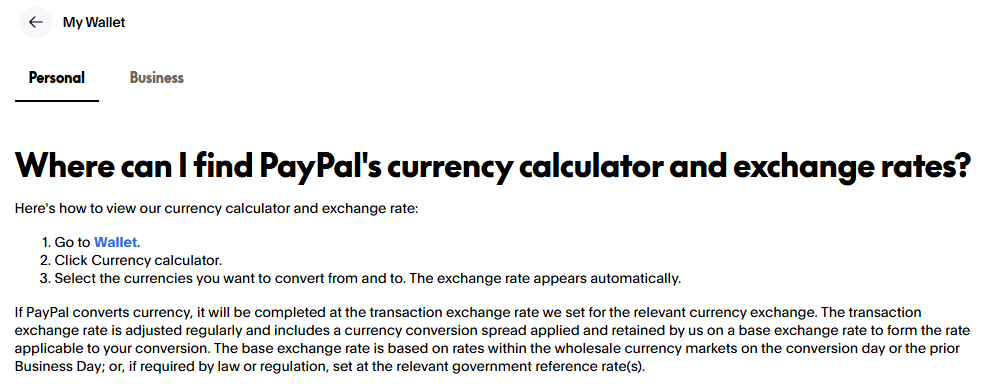
PayPal incorporates the spread into its quoted transaction exchange rate. Its base rate draws on wholesale-market rates from the conversion day or prior business day, or an applicable government reference rate. Do not assume it equals a live search-engine quote. PayPal explains the method in its exchange-rate guidance.
Example: use the quoted rate once
Suppose an eligible US account already holds €200 and converts it into USD. Assume the displayed transaction rate is $1.08 per €1. This rate is hypothetical, not a current PayPal quote.
€200 × $1.08 per €1 = $216.00
If that is the quoted rate after the conversion spread, do not subtract another 3% from $216. The conversion cost is already reflected in the rate. Any separately disclosed withdrawal or other charge would need its own calculation.
To check a rate, use Wallet → Currency calculator and choose the source and destination currencies, following PayPal’s instructions. Review the rate for the actual transaction before confirming; a preview is not a permanent exchange-rate promise.
Can you receive foreign currency without converting it?
Eligible US business accounts can configure supported currencies to be held instead of automatically converted. Review the receiving preferences described in PayPal’s foreign-currency guidance. Holding funds can postpone conversion, but postponement is not the same as eliminating its cost.
The US User Agreement states that balances are withdrawn in USD; funds held in another currency must be converted beforehand or at withdrawal. Do not assume that linking a foreign-currency bank account lets a US PayPal account withdraw that currency unchanged.
Buying from an overseas seller: check your card costs separately
An ordinary overseas checkout purchase is not a Friends and Family transfer. Do not add the personal-transfer percentage to it. However, your card provider may charge for a foreign transaction even without currency conversion, according to PayPal’s cross-border guidance.
For a $100 USD purchase charged to a USD card, distinguish the purchase price from any separately charged issuer fee. The seller’s PayPal receiving fee is not automatically an additional charge on the buyer’s card.
Can your card issuer handle conversion instead?
For some card-funded payments, PayPal offers a choice of conversion provider. Its foreign-currency payment guidance describes changing the conversion choice during payment review. The option is not available for every card, and the issuer’s exact exchange rate may only be available afterward on the statement.
Check the issuer’s conversion method and foreign-transaction charges before deciding. A different conversion provider is not automatically cheaper, and avoiding PayPal’s conversion does not guarantee that the card issuer charges nothing.
How to check the total before you confirm
PayPal’s sending instructions place payment review after choosing the amount, currency, purpose, and funding method. Before authorizing an international payment, check these four things:
- Which transaction are you making? Separate a personal gift from a purchase, client payment, or business bill payment.
- What are you sending versus spending? Record the payment amount and the total sender debit separately. Identify which fee is capped rather than assuming the entire cost is capped.
- Who converts which amount? Note the source currency, destination currency, quoted rate, and expected recipient amount where displayed. Keep every addition and subtraction in the same currency.
- What happens afterward? Check whether the recipient still needs a currency conversion or withdrawal. Do not describe the amount entering PayPal as a guaranteed bank deposit.
For a completed payment, open Activity and select the transaction to inspect its fees, as explained in PayPal’s account-fee help. Compare the recorded payment and conversion details, not an unrelated or combined bank deposit.
If your estimate differs, check the product, account markets, funding source, fixed-fee currency, and any special pricing before blaming rounding. For historical payments, use the schedule that applied on the transaction date.
Ways to reduce unnecessary costs
Compare funding methods for the same payment. In the $1,000 personal example, using balance or bank instead of standard card funding removes $29.30 from the modeled sender cost. It does not remove the international component or settle the recipient’s later expenses.
Agree on the useful receiving currency. Ask what currency the recipient needs and compare the complete routes. Repeated conversions can add avoidable costs, but invoicing in your own currency may simply move conversion to your customer. Holding money for later conversion also means using a potentially different future rate; review PayPal’s conversion rules.
Compare equal outcomes. With another provider or payment route, hold either your total spending or the recipient’s target net constant. A lower advertised fee alone does not establish a cheaper transfer when the exchange rates and eventual withdrawal costs differ.
Keep purchases classified as purchases. PayPal’s payment guidance reserves the personal-payment choice for genuine personal transfers. Its US User Agreement also prohibits a PayPal-acceptance surcharge; calculating costs does not authorize adding a PayPal-only fee.
Do Xoom, Payouts, and business bill payments use these rates?
No—check the service you actually select. Xoom has its own transaction charges and exchange-rate quote. Its fees vary with the destination, funding method, amount, and payout details, according to the Xoom User Agreement. Do not carry the personal-transfer cap into a Xoom quote.
PayPal Payouts and Bill Pay for Business Accounts also have separate sections in the merchant fee schedule. PayPal’s policy updates specifically distinguish the terms for business accounts sending payments for goods and services. The ordinary buyer-checkout example above is not a quote for those business services.
For a useful estimate, identify one payment route and trace its costs from funding through the recipient’s intended use of the money. Keep sender charges, receiving deductions, and currency conversion separate until you can compare them on the same basis.
Last verified: October 18, 2026.